Cost of Production
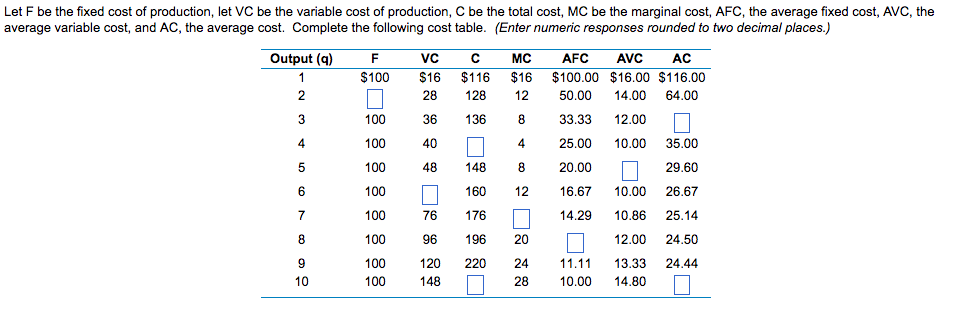
Fixed cost: cost that does not change no matter how much is produced
Variable cost: cost that rises or falls depending upon how much is produced
Total cost: fixed cost + variable cost
Marginal revenue: the additional income from selling one more unit of goods
Marginal cost: the cost of producing one more unit of goods
Total revenue: price multiplied by quantity
You must use these equations
average total cost (ATC)= average fixed cost (AFC) +(AVC) average variable cost
average fixed cost(AFC)= total fixed cost (TFC) / (Q) quantity
ave
rage variable cost (AVC)= total variable cost (TVC) / (Q) quantity
average total cost (ATC)= total cost (TC) / (Q) quantity
total cost (TC)=(TFC) total fixed cost + (TVC) total variable cost
total fixed cost (TFC)= average fixed cost (AFC)(Q) quantity
to
total variable cost (TVC)= average variable cost (AVC)(Q)quantity
total cost (TC)= average total cost (ATC)/(Q) quantity
Comments
Post a Comment